US Christmas 2026: Wholesale and Retail Stock Trends
A product-level look at US Christmas 2026 demand, including collectible toys, building sets, beauty and home hosting, plus categories and familiar brands losing momentum.
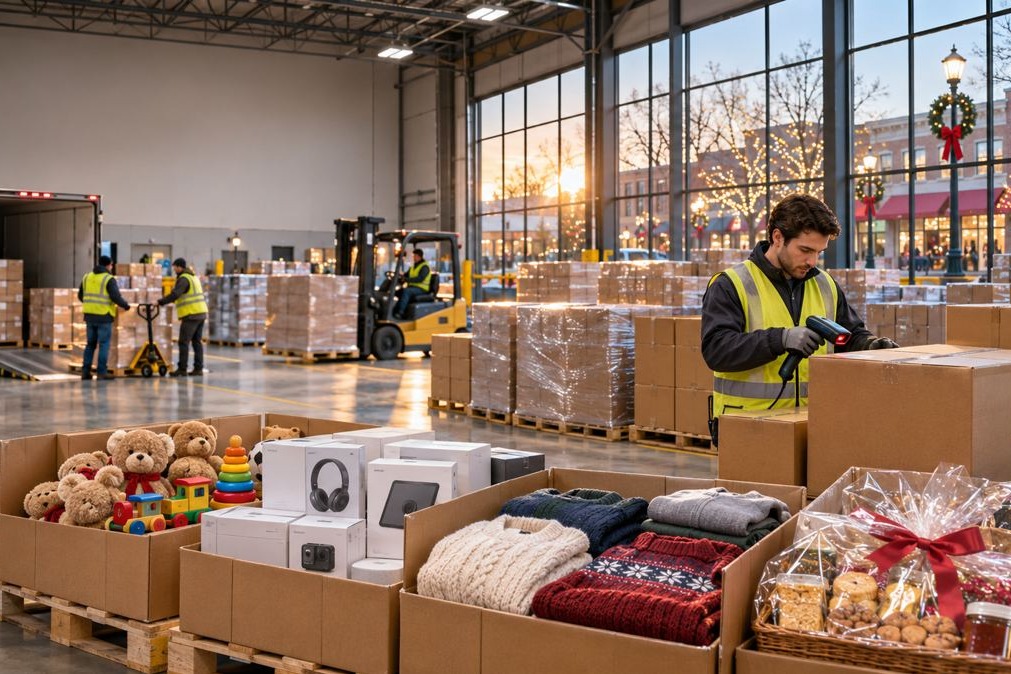
The US Christmas season has a clear split: several specific product groups have strong evidence behind them, while other familiar gift categories are entering the season with weaker momentum than a year ago. The useful signal is at product level. “Toys” and “electronics” are too broad to be buying plans: trading cards and building sets are moving differently from preschool toys, and useful or highly anticipated tech is not the same proposition as a generic gadget.
The overall market is still large. The National Retail Federation forecasts November and December retail sales to grow 4.2% over 2025 to $1.013 trillion. Adobe expects US online sales to reach $275.1 billion, up 6.7%. But the household budget evidence is less buoyant: Circana’s October survey puts expected holiday spending at an average $779, below $796 last year, and 74% of respondents expect to use money-saving measures. Those figures describe different things, so they are not contradictory: sales can rise in dollars while shoppers buy selectively, trade down or pay higher prices.
Where the strongest product evidence sits
Trading cards, collectibles and licensed fandom products: These are among the clearest growth areas in toys. Circana reported that US toy sales rose 17% in dollars and 12% in units in the first half of 2026, the strongest first half in six years. Trading cards and collectibles were major drivers. Licensed toys grew 24% and made up 39% of toy sales. Adult and teen recipients were especially important: toy sales for adults rose 25%, and those for teens rose 33%. This supports demand for recognisable properties, collectible releases and hobby products with an active fan base, not indiscriminate depth across every licensed line.
Specific products appearing on Adobe’s 2026 holiday hot-seller list include KPop Demon Hunters toys, LEGO Pokémon, Jellycat plush, Beyblade X, NeeDoh and Pokémon products. These are useful signals for assortment planning, but they are a forecast shortlist, not a guarantee of local availability or sell-through. Trading cards, sports collectibles and licensed building sets have broader category support than an isolated viral toy.
Collectible games, building sets and creative kits: Circana reports that U.S. sales revenue in its Games & Puzzles supercategory rose 45% year on year in the first half of 2026, with trading cards, collectibles and sports-related products helping drive growth. The release does not report equivalent growth for conventional board games or jigsaw puzzles. Circana separately records Building Sets up 22%, Arts & Crafts up 20%, and Action Figures & Accessories up 10%, with gains across dollars, units and pricing. Licensed sports properties, including FIFA, MLB, NFL and NBA, also posted meaningful gains. The published figures support interest in collectibles, licensed sets and creative products; they do not establish equivalent growth for every board-game or puzzle line.
Beauty, personal care and everyday replenishment: Adobe forecasts online cosmetics sales up 9.5% and grocery up 10.3%, both ahead of its 6.7% overall online growth forecast. Its forecast also points to heavy promotion-driven Cyber Week demand for personal hygiene, household cleaning, baby and pet products. Personal care gift sets, cosmetics, grooming items, household essentials, baby basics and pet products therefore have a seasonal opportunity that does not depend entirely on novelty gifting. The strongest proposition is clear utility at an attractive price, including multipacks and easy-to-understand gift formats.
Food, hosting and useful home products: Circana finds shoppers shifting some plans closer to home, with prepared foods and convenient meal solutions supporting at-home celebrations. JLL’s holiday survey reports planned spending on food and decorations rising 16% year over year, while gift budgets increased only 3.1%. Adobe separately forecasts online grocery growth of 10.3% and furniture growth of 7.3%. These are different surveys and channels, but together they point to practical demand around hosting: food gifts, baking and serving goods, tableware, small kitchen appliances, coffee products, storage and comfortable home items. Large furniture can benefit online, but its delivery and return costs make it a different stock proposition from compact home gifts.
Gift cards and flexible-price gifts: NRF’s survey says 47% of holiday shoppers would like to receive gift cards, ahead of clothing at 44%, books and other media at 25%, and personal care or beauty at 24%. Gift cards are not a physical stock line, but the result is a useful read on uncertainty: shoppers value choice, and a flexible gift can capture spend when a specific product feels risky or the recipient is hard to buy for. Small, broadly appealing gifts and products at familiar price points also fit a season in which more households are managing a fixed budget.
Where last year’s strength is not carrying through evenly
Apparel and footwear: These remain large holiday categories, but current indicators are softer than last year. Adobe forecasts online apparel growth of 4.7%, below overall online growth of 6.7%. McKinsey’s comparison of US spending intentions shows the net intent for apparel at minus 24 points in 2026 versus minus 1 point in 2025, and footwear at minus 22 versus minus 4. These are intentions, not final sales, yet the year-on-year deterioration is substantial. That makes broad speculative depth in fashion styles, sizes and seasonal colours harder to justify than proven basics, replenishment items and value-led lines. Adobe expects strong Cyber Week lifts in clothing basics, a notable contrast with the weaker apparel intent overall.
Consumer electronics as a broad gift bet: Adobe still expects online electronics sales to grow 5.9%, so the data does not say “electronics will not sell.” It does say growth is below the online market average, while JLL found fewer shoppers plan to visit electronics retailers as part of their holiday shopping, 32.2% versus 39% in 2025. McKinsey also found weaker spending intent for home and personal electronics than a year earlier. The risk sits in generic, undifferentiated devices and older models that need deep discounts to compete. Specific high-interest products, gaming hardware and accessories with a clear use case are a different bet; Adobe’s hot-seller list includes new gaming consoles, headphones and selected flagship devices.
Barbie and Fisher-Price assortments should not be treated as the whole toy market: Mattel’s third-quarter 2026 results show global gross billings for Barbie down 9% year over year and Fisher-Price down 14%. For the first nine months, the declines were 13% and 12%, respectively. This is a meaningful warning for those particular brands and segments, especially against the wider toy market’s first-half growth. It is not evidence that all dolls or preschool products are weak: Mattel’s doll category rose 4% in the quarter, helped by partner brands including KPop Demon Hunters, while Hot Wheels rose 7% and its vehicles category rose 9%. The distinction is commercially important: licensed releases, vehicles and collectibles are outperforming some legacy lines inside the same supplier portfolio.
Expensive discretionary gifts without a clear reason to buy: Circana reports that 74% of consumers expect to save money through promotions, store brands or reduced discretionary spending. JLL finds that more shoppers plan to buy gifts for fewer people than last year. A high ticket alone is not a demand signal. Premium gadgets, decorative novelties and fashion-led gifts without a strong brand, function or personal connection face a tougher conversion test. This does not make premium goods unviable; it narrows the opportunity to products whose benefits are immediately clear and whose price is supported by brand, quality or a specific recipient interest.
The practical Christmas assortment picture
The strongest stocking case is concentrated in trading cards and collectibles, licensed toys with active fandoms, building sets, games and puzzles, arts and crafts, selected sports products, beauty and personal care, everyday essentials, grocery and compact hosting goods. These categories have either recent measured growth, a favourable holiday forecast, or both.
The more cautious side is broad apparel and footwear depth, undifferentiated consumer electronics, and blanket assumptions that every familiar toy brand will repeat its past performance. Current evidence points to weaker apparel and footwear spending intentions, slower forecast growth for electronics than e-commerce overall, and sharp differences among individual toy franchises. The signal is not to abandon these categories, but to be much more exact about the product, price and brand.
That is the key difference between a growing season and an easy season. National sales forecasts remain positive, but households are choosing where to spend. Stock opportunities are strongest where a product combines a recognisable reason to buy with a defensible price: fandom, collecting, creativity, practical use, self-care or making a celebration easier. Familiarity alone is a weaker reason to commit inventory this Christmas.
Sources
- National Retail Federation, 2026 holiday sales forecast, 15 October 2026
- Circana, 2026 holiday purchase intentions, 8 October 2026
- Circana, US toy industry first-half results, 12 August 2026
- Adobe, US online holiday shopping forecast, 28 September 2026
- McKinsey, US holiday budgeting and category spending intentions, 2026
- Mattel, third-quarter 2026 financial results, 5 November 2026
- JLL, 2026 US holiday shopping report, October 2026